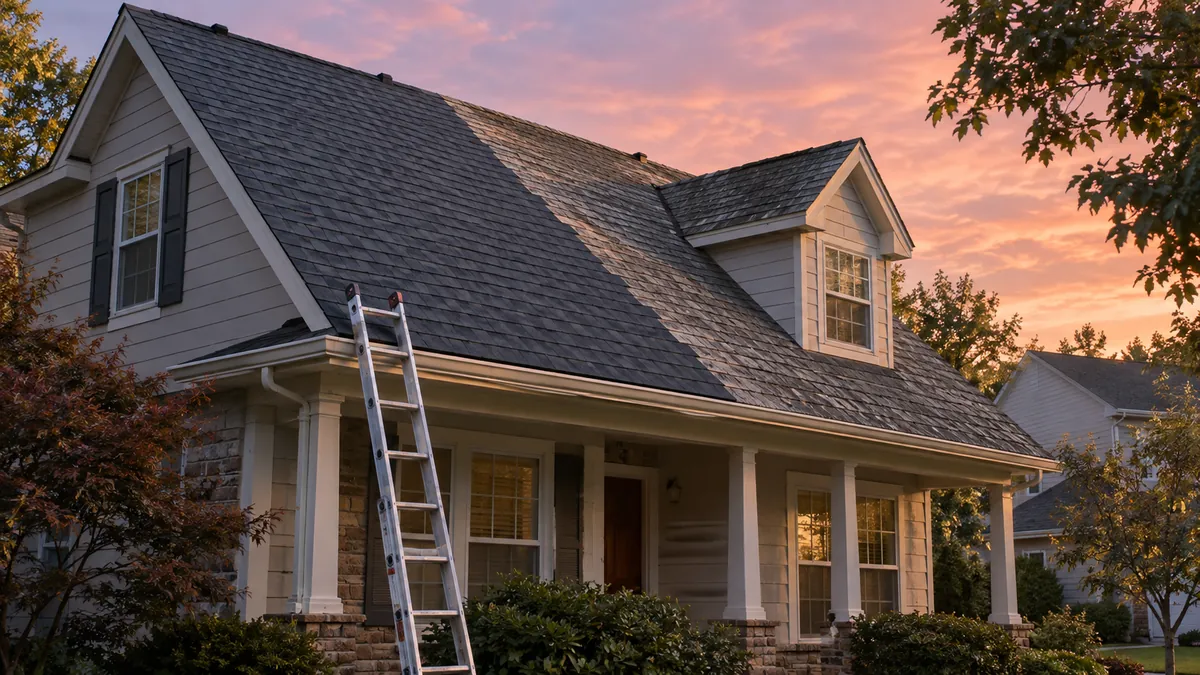
A Texas buyer is closing next week. Somewhere in the middle of the process, the agent tells him the roof is going to make the house uninsurable (and unlendable) unless it gets replaced. So the seller replaces it.
Deal saved, right?
Except now the new roof is a different color than the rest of the house, the buyer hates it, and he's asking the internet if he can walk away from the contract over shingle color. Two thousand-plus upvotes and over 1,500 comments later, everybody's got an opinion on the color.
Nobody's talking about the actual story: the roof almost killed this deal, and it had nothing to do with paint chips.
Why a roof can end a purchase before you ever get to the color debate
Insurance carriers underwrite roofs hard right now. Age, material, and condition all matter, and a lot of carriers will flat-out decline or heavily restrict coverage on a roof that's aging out, showing curling shingles, algae staining, or prior hail damage, even if the rest of the house is in great shape.
Here's the part buyers miss: no insurance commitment usually means no mortgage commitment. Lenders require proof of insurance to fund. If nobody can bind a policy on the roof as it sits, the loan doesn't close, full stop. That's not a nitpick from your agent. That's the whole transaction on the line.
What I want buyers doing differently
1. Get the house actually quoted for insurance (not just "assumed insurable") before you drop your inspection contingency.
A verbal "it should be fine" from an agent isn't the same as a real quote from a carrier. Roofs are one of the fastest ways a house that looks fine goes sideways in underwriting.
2. If a roof gets replaced to satisfy insurance, get the specs in writing before the work happens.
Material, brand, color, warranty: all of it. That protects you on the color surprise, and it also gives your new policy accurate, documented details instead of a guess.
3. A replaced roof doesn't automatically mean you're covered.
Get it re-quoted after the replacement. The carrier needs the new roof's actual details on file, not the old ones from before closing.
The takeaway
The color fight is the fun part to argue about online. The insurance timing is the part that actually decides whether you close. Line those up early and you never end up negotiating shingle color under a 24-hour contingency clock.
If you're under contract right now and haven't had the home actually quoted for insurance yet (not assumed, quoted), send it my way. I'll run it before your contingency deadline runs out, not after.
Michael Gordy
INS. (In Noble Service)
Michael@ins.insure | 678-578-7009